

Together Loans
Transform Credit Inc
- 4.3
- 272.00 Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
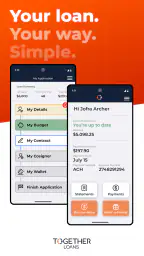
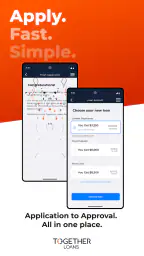
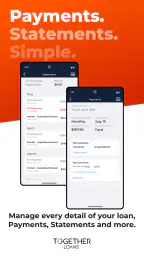
Together Loans Pros and Cons
Pros
- Simple loan application process with clear repayment information.
- Useful option for borrowers with limited traditional credit history.
- Mobile access makes it easy to manage loan details on the go.
- Potentially flexible loan offers based on individual financial profiles.
- Helpful repayment reminders can reduce the risk of missed payments.
Cons
- Approval and interest rates depend heavily on your credit profile.
- Loan availability and terms may vary by state or country.
- Late payments can lead to extra fees and credit score damage.
- Personal and financial information is required during registration.
- Some users may receive less favorable terms than expected.
 Analysis by All-app
I approached Together Loans as a borrower would: not looking for a general budgeting tool, but for a focused way to stay on top of an existing loan. That distinction matters. The app is made by Transform Credit Inc and sits in the finance category, with its purpose centered on managing a loan in one place rather than replacing a full banking app.
My overall impression is that its value depends on a simple question: do you already have a Together loan that you need to monitor? If the answer is yes, a dedicated account-management app can be less distracting than navigating a wider banking service. If the answer is no, there is little reason to install it just to explore. It is a practical companion for an existing borrowing relationship, not a broad personal-finance dashboard.
The app is free to download, is rated for Everyone, and has reached over one hundred thousand installs. Its average rating is 4.3 from more than six hundred ratings, which suggests that many users find the basic experience useful while still leaving room for individual frustrations. I tested it with a deliberately practical mindset: how quickly can someone get from opening the app to understanding what needs attention, and what should they check when that process does not go smoothly?
Where people usually get stuck
The first point of friction is often expectation. Someone may install the app expecting to apply for a new loan, compare products, or manage several unrelated financial accounts. That is not the role I would assign to it. The store summary describes it as a place to manage your loan, so the most sensible starting point is an existing Together loan and the account details connected to it.
That narrow purpose is actually a strength when used correctly. A loan-management app should help you focus on the information that affects repayment, rather than burying it among card spending, savings goals, investments, and notifications from other financial products. The trade-off is that it will not serve as a replacement for your everyday bank app or a complete household budget planner.
Another common stumbling block is treating sign-in trouble as proof that the app itself is broken. Financial apps often depend on matching account information, a stable connection, and a successful verification step. A mistyped detail, an old contact address, or an interrupted session can look very similar to a technical failure. I would first slow down and check each part of the process before repeatedly attempting the same action.
It also helps to separate three different problems. One is access: you cannot get into the account. Another is display: you can enter the app but cannot see the information you expected. The third is action: the account is visible, but a particular task does not complete. Each calls for a different response, and reinstalling immediately is rarely the best first move.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
What to check before blaming the app
Before opening the app, I would have the relevant loan information nearby and make sure I am using the same personal details associated with the account. This is particularly useful when a person has more than one email address, has recently changed contact information, or normally relies on a password manager that may fill an outdated entry.
The next check is the device itself. Together Loans supports Android devices running Android 7.0 or later, so an older phone may be the reason installation or updating is unavailable. On a compatible phone, I would confirm that the app has finished installing, that the operating system is not waiting for a restart, and that there is enough storage for ordinary app updates.
Connection quality deserves attention too. A weak mobile signal or an unstable public Wi-Fi network can interrupt account verification even when other apps appear to work. For a financial account, I prefer trying again on a trusted, stable connection rather than repeatedly switching between networks. If the screen remains unchanged, closing the app fully and reopening it is a sensible low-risk step.
There is also a security trade-off in troubleshooting. I would not send loan details, passwords, or verification codes through an informal message or share screenshots containing personal information. If support is needed, I would use the official route associated with the account and describe the problem without exposing sensitive credentials. The convenience of quick help is not worth weakening account security.
A calmer setup routine
My recommended setup is deliberately unexciting. Install the current version, which is 9.1.2, on a supported device, open it on a reliable connection, and read each prompt instead of tapping through automatically. If the app asks for information that you recognize from your loan relationship, enter it carefully and check for spaces or spelling errors before submitting.
Once access is established, I would spend a few minutes looking around without trying to change anything. The goal is to learn where the important loan information appears and how the app presents account status. That small orientation step becomes useful later, because you can tell whether a missing screen is genuinely unusual or simply located somewhere you have not opened yet.
I would also make sure the phone itself is protected with a screen lock. A loan-management app may be convenient precisely because it keeps important account information close at hand, but that convenience increases the importance of basic device security. Avoiding shared devices is another sensible precaution, especially if the phone is used by family members or coworkers.
Notifications should be treated as reminders, not as the only record of a financial obligation. If a notification is delayed, dismissed, or never appears, that should not be the reason you miss an important date. I would use the app as a convenient place to review the account while keeping my own reliable reminder system for anything that affects my monthly planning.
Recovering from a failed or incomplete workflow
When an action appears to fail, I would first check whether the app has actually returned to a stable account screen. Sometimes a slow connection creates uncertainty: the user does not know whether to try again, while the service may still be processing the first attempt. Waiting briefly, checking the account status, and avoiding repeated submissions is safer than tapping the same control several times.
If the app closes or becomes unresponsive, I would reopen it and see whether the previous state was preserved. If the problem is limited to one session, a fresh launch may be enough. If it happens repeatedly, I would note the exact step, the wording of any message, and whether the issue occurs on Wi-Fi, mobile data, or both. That information is far more useful than reporting only that “the app does not work.”
Updating the app is another reasonable recovery step, especially when the installed version is older than the current release. I would update through the normal app store process, then restart the app and repeat the task once. I would avoid downloading unofficial copies or tools that claim to repair the account, because financial credentials should never be handed to an unknown service.
Reinstalling can help with damaged local app data, but I would place it later in the process rather than making it the automatic solution. Before removing the app, I would make sure I know how to sign in again and have access to the contact method connected to the account. Otherwise, a simple troubleshooting attempt could create a more frustrating access problem.
One useful habit is to record what you were trying to do before starting recovery. Were you checking the loan, attempting an account action, or simply opening a notification? That distinction helps reveal whether the issue is repeatable. It also prevents the common mistake of changing several things at once and then not knowing which step solved the problem.
When the app is not the cause
Not every delay belongs to the mobile application. Account information may depend on the underlying loan service, identity checks, scheduled processing, or a temporary interruption outside the phone. If the app opens normally but a specific piece of information is delayed or inconsistent, I would avoid assuming that reinstalling will change the underlying account state.
The same applies when information looks unfamiliar. Before treating it as a display error, I would compare it with the paperwork or correspondence connected to the loan and check whether I am viewing the correct account. If something remains unclear, the appropriate next step is to contact the lender through a trusted official channel rather than trying random settings or third-party financial tools.
Device conditions can also imitate app problems. An outdated operating system, extremely limited storage, aggressive battery restrictions, or a network that blocks certain connections may interfere with normal use. These are not reasons to panic, but they are good reminders that a finance app sits inside a larger chain of device, network, account, and service dependencies.
I would be especially cautious if an unexpected message asks for sensitive information or urges immediate action outside the normal app experience. The safest response is to stop, avoid using the supplied contact details, and verify the request through an official route you already trust. A clean interface cannot protect someone who voluntarily gives away a password or verification code.
How it compares with ordinary alternatives
The usual alternative is to manage the loan through a browser or through general banking tools. A browser may be preferable when you need to print information, work on a larger screen, or use several financial services at once. A general banking app is better for seeing the loan alongside spending, bills, and savings. Those options offer breadth, but they may also require more navigation.
Together Loans makes more sense when the task is narrow and repeated: open the dedicated service, check the loan information, and leave. That can be useful for someone who does not want loan details mixed into a busy banking dashboard. The trade-off is that you now have another finance app to maintain, update, and secure, and it will not replace the broader planning tools found elsewhere.
For a person who wants debt payoff projections, category-based spending analysis, or a combined view of multiple lenders, I would choose a broader personal-finance solution instead. For someone who only needs access to an existing Together loan account, that broader solution may feel unnecessarily complicated. The right choice depends less on the app’s rating and more on whether its focused purpose matches your routine.
Everyday situations where it earns its place
Imagine checking your finances before a rent payment. You want to review the loan account without opening a full banking dashboard and getting distracted by unrelated transactions. A dedicated app can make that check feel more deliberate: open the account, confirm the information you need, and close it. I would still compare the result with my own budget and reminders rather than treating one app as the complete picture.
Another useful situation is preparing for a conversation about your finances. Instead of searching through old messages or browser tabs, you can first review the account in its dedicated space and note what needs clarification. The important benefit is not that the app makes financial decisions for you; it gives you a more direct place to start gathering the information needed for your own decision.
It can also help someone who tends to forget where loan information is stored. A separate app creates a clear mental association between the icon and the account. That is a small usability advantage, but it matters when financial tasks are already competing with work, family, and everyday errands.
At the same time, I would not recommend relying on it alone for a complete repayment strategy. The app is best used as one part of a routine that includes a personal budget, calendar reminders, and careful review of official account information. Keeping those separate checks may feel less convenient, but it protects you from assuming that a missing notification or temporary display issue means nothing needs attention.
Who should install it and who should skip it
I would recommend it to an existing Together borrower who wants a focused mobile route to loan management and prefers a dedicated experience over a general banking dashboard. It is also a reasonable choice for someone who mainly uses an Android phone and wants a straightforward account companion without paying to download the app.
I would skip it if you are looking for a loan comparison service, a general budgeting app, or a single place to combine accounts from different providers. It is also not the best fit for someone who rarely uses a phone for financial tasks and would rather handle everything in a desktop browser. Installing another app does not automatically simplify a routine that already works well.
The Everyone content rating makes it broadly accessible from an age-classification standpoint, but that should not be confused with financial suitability. Borrowing decisions still require adult judgment, attention to repayment obligations, and a clear understanding of the account being managed. The app can organize access; it cannot decide whether a loan is affordable or appropriate.
My practical verdict
After looking at the app through the lens of setup, recovery, and everyday use, I see Together Loans as a focused tool rather than an all-purpose finance solution. Its strongest quality is concentration: if your financial task is managing a Together loan, the app gives that task its own place instead of making you search through unrelated services.
The main limitation is equally clear. Its usefulness depends on having the corresponding loan relationship and on keeping your account details, device, connection, and security habits in order. When something goes wrong, the best response is usually methodical: verify the account details, check device compatibility, use a stable connection, update safely, and distinguish an app problem from an account or service issue.
With that realistic expectation, I would recommend trying it to an existing borrower who wants convenient mobile access. I would not present it as a replacement for a bank, budget planner, or financial adviser. Used for the narrow job it is designed to handle, it can be a sensible free addition to a repayment routine. Used as a complete view of your finances, it will feel limited.
Transform Credit Inc has kept the idea easy to understand: the app is for managing a loan, not for turning every financial task into one crowded dashboard. That simplicity is what makes it worthwhile for the right person. My advice is to install it only when it matches your actual account, set it up carefully, keep independent reminders, and judge it by whether it makes your regular loan check quicker and clearer.
Frequently Asked Questions
What is Together Loans, and how does the app work?
Together Loans is a digital lending service designed to help users explore personal loan options through an online application process. After entering information such as your identity, income, employment, and requested amount, the service may assess your details and present available options from lending providers. It is important to understand that Together Loans may act as a broker rather than the actual lender, so terms, approval decisions, and customer service can vary.
Can I be approved for a loan through Together Loans?
Approval is never guaranteed when using Together Loans. Eligibility normally depends on factors such as your age, residency, income, employment status, credit history, existing financial commitments, and the amount you request. Even if the service matches you with a provider, the lender can still carry out additional checks and decline the application. Read the eligibility requirements carefully before submitting your personal information.
How much does a loan through Together Loans cost?
The cost depends entirely on the lender and the offer you receive. Before accepting anything, check the interest rate, representative APR, arrangement or broker fees, late-payment charges, repayment schedule, and total amount repayable. A loan with a lower monthly payment can still be expensive if the term is long. Never rely only on promotional figures; review the complete agreement and confirm the final cost.
Is Together Loans safe to use, and what personal information is required?
As with any online financial service, use Together Loans only after confirming that you are on the official website or app and that the connection is secure. Loan applications commonly request sensitive details, including contact information, employment and income data, bank details, and identification information. Review the privacy policy to understand how data is shared with lending partners, and avoid providing information through unofficial links or messages.
What should I check before accepting an offer from Together Loans?
Before accepting an offer, compare the APR, interest rate, repayment period, monthly instalments, total repayment, fees, and consequences of missing payments. Make sure the instalments fit comfortably within your budget, including during emergencies or changes in income. Also verify the lender’s name, cancellation rights, contact details, and any credit-check implications. If the terms are unclear or pressure is applied, do not proceed until you have independent advice.


